
GEORGETOWN, Guyana – The Guyana economy grew by 33.3 per cent during the first half of this year with strong performances being recorded across the various sectors, President Irfaan Ali said on Monday.
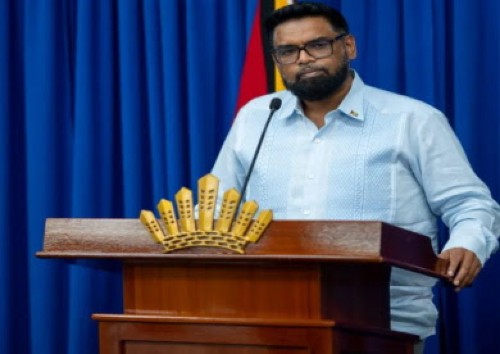 President Irfaan Ali speaking at news conference on the state of the local economyHe told a news conference that the performance reflects growth against an already significantly expanded economic base and that the non-oil sector also recorded an estimated growth of 10.1 per cent, marking the sixth consecutive year of expansion.
”Our overall GDP (gross domestic product) grew by an estimated 33.3 per cent in the first half of 2026. The non-oil economy grew by an estimated 10.1 per cent,” Ali said, noting that the strong first-half performance has prompted a revision of Guyana’s full-year real GDP growth forecast to 20.8 per cent, while non-oil GDP is projected to expand by 10.2 per cent.
According to the figures released here, growth was broad-based, with the mining and quarrying sector expanding by an estimated 40.7 per cent. The oil and gas subsector grew by 41.3 per cent, while other mining activities, including sand, stone, manganese and diamond, expanded by 40 per cent. Gold and mining recorded estimated growth of 11.3 per cent.
Construction expanded by 24.7 per cent, while services grew by 7.2 per cent and manufacturing by 3 per cent.
President Ali told the reporters that the expansion is translating into increased economic activity, investment and opportunities, underscoring the link between industrial development and improved household prospects.
“Industries lead to jobs. Jobs lead to more income. More income leads to better economic prospects. And that’s how the economic cycle works,” he added.
The half year financial report showed that while agriculture, forestry and fishing collectively contracted marginally by 0.5 per cent amid higher transportation and input costs and challenging weather conditions, several subsectors registered growth.
Sugar expanded by 19.3 per cent, rice by 4.4 per cent, forestry by 15.4 per cent and fishing by 4.1 per cent.
Net domestic credit stood at GUY$1.286 trillion (One Guyana dollar=US$0.008 cents) at the end of June, representing a 15.5 per cent increase over the December 2025 position.
Credit to the private sector grew by 11.5 per cent, while real estate mortgages expanded by 21.2 per cent.
Ali said the cumulative indicators point to an economy demonstrating resilience, diversification and structural strength.
“Isn’t this an economy that is healthy? Isn’t this an economy that is demonstrating strength, that is demonstrating diversification, that is demonstrating structural stability?”
He said that despite the significant pace of expansion, the government continues to focus on ensuring economic growth translates into tangible improvements in citizens’ lives, with the president reiterating his commitment to expanding opportunities for households.
“The people of Guyana, every household, will surely, most definitely, see not only enormous improvement in their personal life but enormous policies and programs that will enhance their ability of owning more things and, of course, advancing their own life,” Ali told reporters.
He said that the Guyana Development Bank (GDB) will become operationalised on October 5, at capitalised at US$100 million.
The government said that through affordable financing options, including zero-interest and zero-collateral loans of up to three million Guyana dollars for eligible borrowers, the development bank will support Guyanese seeking to establish or expand businesses in key sectors such as agriculture, agro-processing, manufacturing, tourism, services and technology.
The bank’s launch comes against a backdrop of expanding financial inclusion. Between October 2024 and August 2026, a total of 179,758 new bank accounts were opened across Guyana’s six commercial banks and two non-bank deposit-taking institutions with 96 per cent in the banking sector proper.
Of that total, 59,951 accounts were opened between April and August 2026 alone, a jump the head of state linked to recent easing of requirements for opening accounts.
Meanwhile, President Ali has announced that the New York-based Citibank will establish a presence in Guyana describing the development as another indication of the country’s growing prominence within the regional and global economic landscape.
He told reporters that Citibank’s establishment here comes against the backdrop of an economy undergoing significant transformation, with expanding investment, new industries and major development projects creating greater demand for sophisticated financial services.
“I’m going to try to push it to an hour, where the representative bank, Citibank, will establish its footprint in our beautiful Guyana,” President Ali said, adding that the country’s economic trajectory is positioning Guyana as an increasingly important destination for international business and investment.
President Ali also linked Citibank’s presence to broader efforts to mobilise international financing for transformative national development, adding that discussions with international partners are advancing a framework that would combine government-to-government financing with international financial resources.
“More importantly, we have been able to work on the establishment of a framework that would bring together government to government financing, and also integrate international financing,” President Ali said, adding that the framework is expected to facilitate major projects with national, regional and global significance and accelerate their implementation.
Ali said Guyana’s growing economic profile and international partnerships are creating opportunities that will have a lasting impact on the country’s development, adding that the government expects further progress to become evident in the coming weeks.